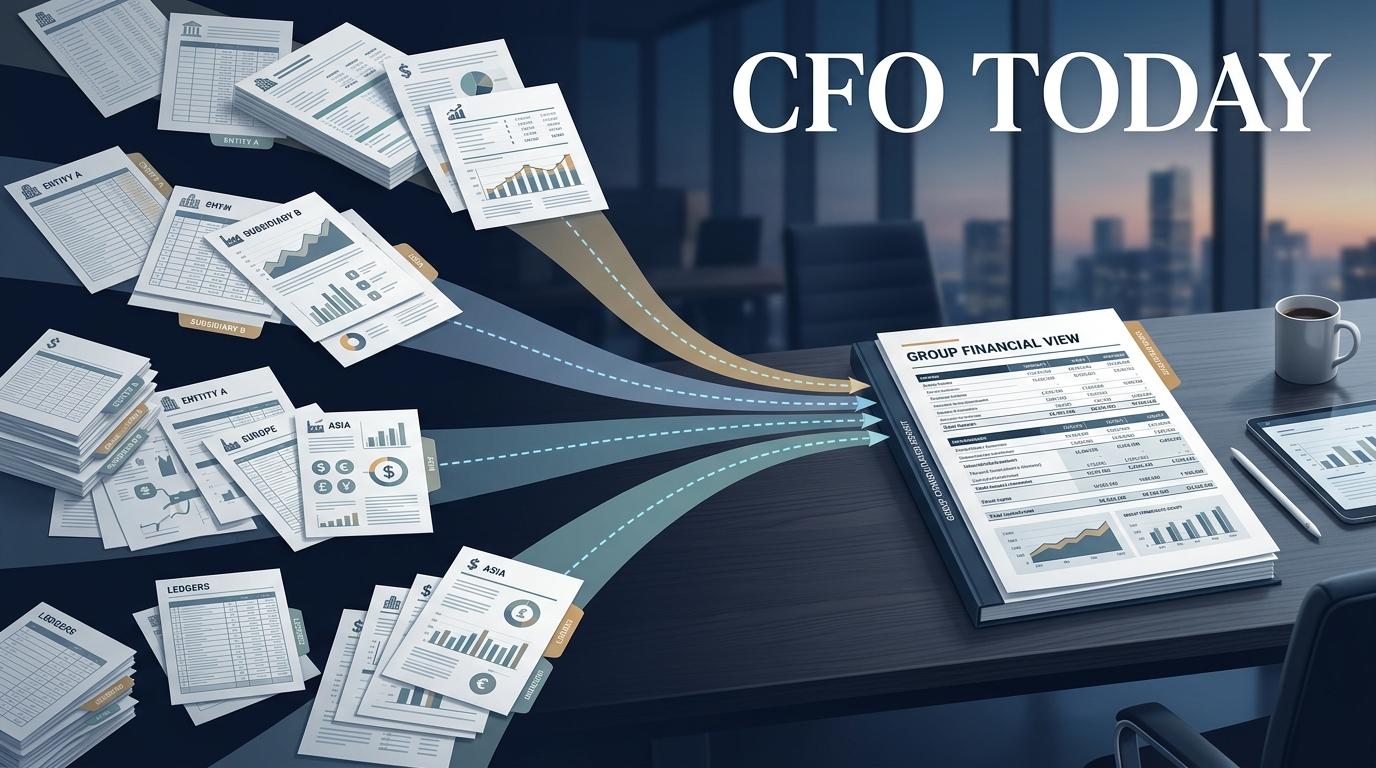
Four subsidiaries can each send finance a correct report and still leave the CFO unable to answer a basic question: what did the group earn this month? Accounts may use different names, periods may have different close status, and a local total may include intercompany activity that should not appear as external group revenue. Financial data consolidation is the work of resolving those differences before leaders rely on the result.
For an early diagnostic, start with Softype’s Multi-Entity Consolidation Readiness Checklist. It helps finance leaders identify where the close depends on manual mapping, reconciliation, or repeated data checks.
Financial data consolidation is the controlled process of aligning, validating, translating, and combining financial information from multiple entities or systems into a comparable group view. It includes agreed reporting definitions, account mapping, entity and currency rules, intercompany reconciliation, supported adjustments, and review. The result should preserve traceability from group totals to entity submissions and source activity. Combining files alone does not establish that the figures are comparable or complete.
Local reports answer questions within their own settings. Group reporting asks whether those separate outputs can be interpreted together. Imagine one entity records “Sales,” another uses “Product Revenue,” and a third includes delivery charges in revenue while the others report delivery as expense. Adding the three lines produces a total, but not necessarily a consistent measure of external revenue.
The same issue appears in reporting periods, dimensions, and data quality. One subsidiary may have closed its books while another has late journals pending. Departments, regions, or business units may have different codes or definitions. A file can load without error while containing duplicate activity, unmapped accounts, a missing counterparty, or a transaction posted to the wrong period.
Finalized consolidated financial statements have framework-specific requirements. IFRS 10, the International Financial Reporting Standard for consolidated statements, bases consolidation scope on control and requires uniform accounting policies for like transactions in similar circumstances. Management reporting may include provisional periods or internal measures, but should state its basis and status; a preliminary group pack is not automatically a finalized financial statement.
Spreadsheets can be useful working papers. The distinction is whether recurring rules, exceptions, and approvals can be reproduced and reviewed rather than reconstructed from scratch each close.
Control area | Spreadsheet-led approach | Governed process |
|---|---|---|
Account consistency | Accounts reclassified manually in each workbook | Approved local-to-group mappings; new accounts flagged |
Entity submissions | Email files with unclear versions or close status | Calendar, submission stages, cutoffs, and resubmission rules |
Currency treatment | Rates pasted into files with uncertain type or period | Approved rates, translation policy, and adjustment history |
Intercompany reconciliation | Balances netted or eliminated before differences are resolved | Counterparties matched, exceptions owned, eliminations supported |
Traceability | Totals depend on links among workbook versions | Sources, mappings, journals, translations, and approvals retained |
Review effort | Reviewers rebuild calculations and inspect many lines | Checks surface exceptions for focused review |
A governed process does not require banning spreadsheets or forcing local teams into identical operational routines. It requires reliable controls around how source information becomes a group result.
Start with definitions, not an integration diagram. Finance should document what the group means by revenue, cost of sales, gross margin, operating expense, and cash. Distinguish external from intercompany activity, and define dimensions such as entity, department, product, region, and business unit. If “gross margin” includes freight for one unit but excludes it for another, comparisons will remain unreliable even after the data reaches one reporting tool.
Finance owns these meanings and the accounting judgments behind them. IT and data leaders help represent the definitions in source connections and transformations. If a local account combines several economic activities, identify whether the source has enough detail to split it. Do not invent granularity that was never captured.
Maintain a controlled mapping from source entity and local account to the group chart of accounts and reporting lines. The Philippines entity’s “4100 Sales,” Singapore’s “40010 Product Income,” and Australia’s “4-1000 Trading Income” may all map to group product revenue after finance confirms that they represent comparable activity.
Assign mapping owners and approvers, preserve effective dates and change history, and show unmapped accounts as exceptions. Reconcile the imported trial balance to the source before mapping, then reconcile the mapped balances to the loaded group view. When amounts differ, investigate rejected transactions, duplicate loads, late postings, and changed extracts rather than quietly patching the total. Oracle’s Financial Consolidation and Close documentation describes integration mapping rules that translate source data into a target format.
Maintain an authoritative entity register with parent relationships, ownership or control assessment, consolidation treatment, local or functional currency, reporting calendar, and effective dates. A newly acquired company should not appear to belong to the group for a full year simply because its current trial balance is available.
For multi-currency consolidation, document the group presentation currency, rate source, rate types, relevant periods, and accounting treatment for translation differences. IAS 21, the IFRS standard on foreign exchange, addresses exchange rates and translating financial statements into a presentation currency. Do not convert every balance using a convenient single rate; the appropriate method depends on the item and applicable framework.
If Entity A records a $1.25 million receivable from Entity B while B records a $1.21 million payable, eliminating the full amount would conceal a $40,000 mismatch. The difference could reflect timing, an unrecorded invoice, a credit note, tax, currency movement, or an incorrectly coded counterparty.
Identify both entities and their counterparty, match balances or transactions, assign and resolve differences, then post supported eliminations. Internal sales, expenses, loans, and balances do not automatically represent external group activity. IFRS 10 requires intragroup balances and transactions to be eliminated in finalized consolidated financial statements. The order matters: identify, match, reconcile, correct or explain, then eliminate.
For product-specific mechanics in NetSuite OneWorld, see the NetSuite OneWorld: Multi-Entity & Multi-Currency ERP Guide. The operating system may vary; the need to resolve differences before relying on a group result does not.
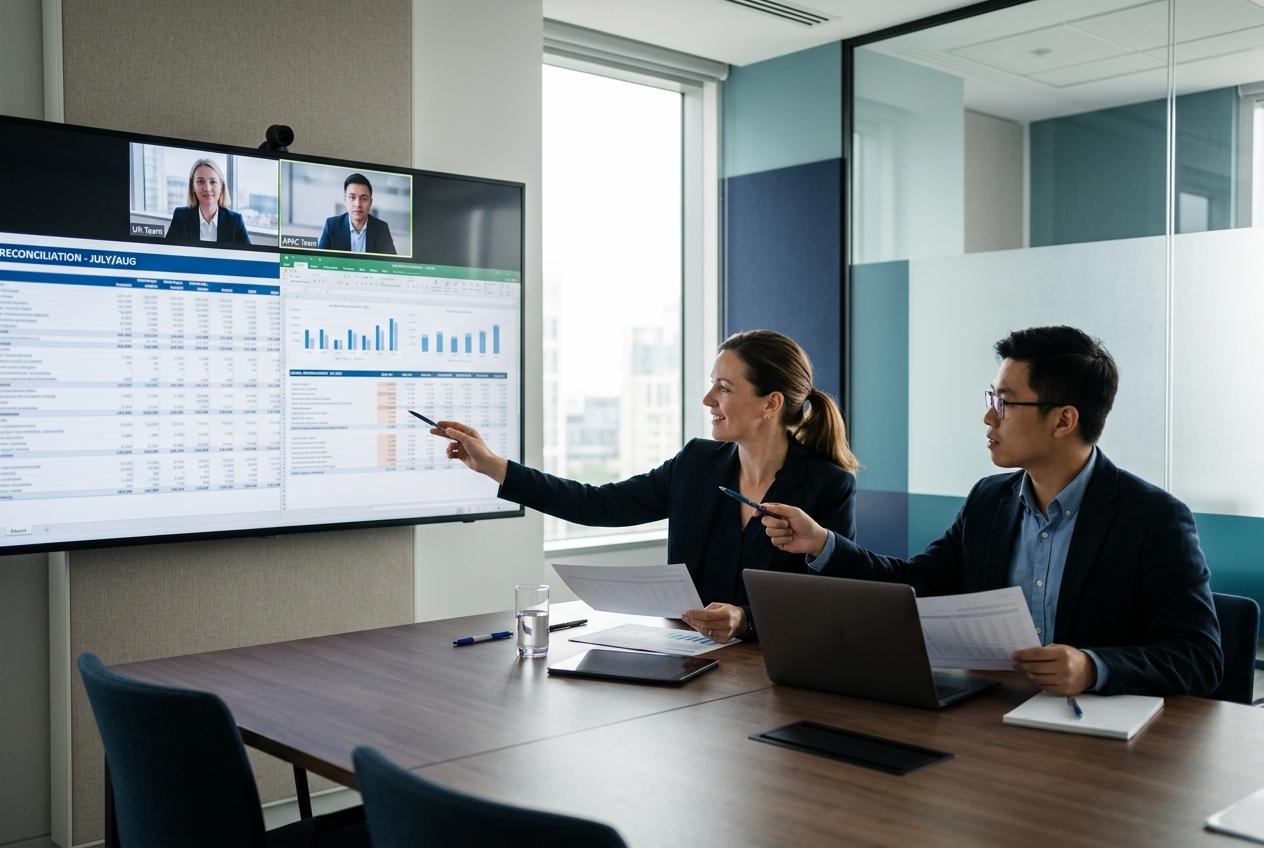
Give each entity a reporting calendar, submission owner, cutoff, and visible status: not received, received, validation failed, corrected, approved, or reopened. Define how finance handles a late journal after submission. A group report should not silently combine closed books with preliminary information.
Checks should flag unbalanced trial balances, missing mappings, invalid reporting dimensions, unavailable exchange rates, duplicate loads, unmatched intercompany amounts, and unusual movements. A 30% revenue change is a reason to investigate, not proof of an error. Every exception needs an owner, resolution, and review status.
Keep separate layers for local reported results, reclassifications, group adjustments, currency translation, and eliminations. In an illustrative example, a subsidiary’s $8.0 million profit could become $7.2 million after $0.3 million of approved group adjustments and $0.5 million of eliminations. Preserve the original submission and supporting details so reviewers can explain the bridge without overwriting source books.
A single source of truth for finance is not simply one screen showing a final number. It is a versioned, defensible path from the group total to contributing entities, local accounts, reporting dimensions, source submissions, and—where available—transactions. If consolidated travel expense is $4.7 million, finance should be able to identify entity contributions, explain reclassifications, and locate the source balances or supporting references.
Traceability also explains change. Did a late accrual alter the submitted balance? Did a mapping move a cost into another reporting line? Did a different approved currency rate create a translation movement? Record the reason, preparer, approver, and report version. Softype’s published OneWorld guide describes an implementation case with a 15-day close involving manual intercompany eliminations; that example illustrates why process controls matter, not a guaranteed result from any tool.
For the separate question of reporting speed, read Real-Time Financial Reporting: Why Month-End Is No Longer Fast Enough. Current information can support decisions, but faster refreshes do not replace reconciliation or turn a provisional figure into a finalized result.
Businesses may have good reasons to keep different accounting, payroll, billing, procurement, or operational systems. A governed reporting process establishes clear source ownership, dependable submissions or integrations, approved definitions, reconciliations, exception handling, and sign-off above those systems. It does not require moving every local process into one application.
A shared ERP can simplify entity structures, account frameworks, and period controls. It cannot by itself repair bad master data, inconsistent account use, incomplete transactions, or weak intercompany discipline. Finance should own the reporting model, accounting judgments, adjustments, and approval. IT and data teams should support connections, transformation logic, access, monitoring, and recovery of prior versions. Both teams need clear ownership for failed loads and changes after close. For a platform-specific overview, see Softype’s Multi-Entity Financial Consolidation on NetSuite.
Use this checklist in a joint finance-and-IT review. Assign an owner and target date for each gap, especially where the process depends on one person’s offline workbook.
Source-system ownership: Is each entity’s source, extract owner, and included financial population documented?
Reporting calendar: Are cutoffs, submission deadlines, close states, resubmission rules, and sign-off dates explicit?
Common account mapping: Are local accounts mapped to approved group lines, with new or unmapped accounts flagged?
Entity and currency rules: Are hierarchy, consolidation scope, effective dates, functional and presentation currencies, rates, and translation policy approved?
Intercompany matching: Can both sides identify their counterparty, reconcile differences, and support eliminations?
Validation checks: Do source-to-load totals, balanced trial balances, required dimensions, duplicates, missing rates, and unusual movements receive review?
Exception ownership: Does each failed check have a responsible owner, status, and resolution history?
Sign-off: Are adjustments and exceptions approved by named preparers and reviewers before the report is presented?
Traceability: Can a reviewer follow a group figure through mappings and adjustments to the entity submission and source activity?
The readiness test is simple: if a senior leader challenges consolidated revenue, can finance explain which entities and accounts contributed, what was translated or eliminated, which submissions were approved, and what source activity supports the total—without rebuilding the answer manually?
It is the controlled alignment, validation, translation, and aggregation of financial information from multiple entities or systems into a group view. A dependable process retains the scope, period, definitions, and traceability behind material totals.
A sum cannot resolve differences in accounts, definitions, currencies, cutoffs, or close status. Spreadsheets can support the work, but mappings, source checks, intercompany reconciliation, versions, and approvals must still be controlled.
Define group reporting lines and dimensions, map local accounts to those lines, and document exceptions and effective dates. Local operational processes can differ where justified; the group’s reporting definitions should remain consistent.
Currency translation requires approved rates and an accounting policy appropriate to the reporting basis. Intercompany activity needs counterparties, matching, investigation of differences, and supported eliminations so internal activity is not mistaken for external group performance.
No. A governed process can consolidate information from several operational and accounting systems. A common platform may reduce some handoffs, but it does not replace common definitions, source quality, reconciliation, and review.
Retain source submissions and versions, mappings, translation rules, journals, approvals, and references to ledger or transaction detail. Reconcile each handoff so the path from group line to source balance can be reproduced.
Management reporting may include internal measures, estimates, or provisional periods when clearly labeled. Finalized statements follow the applicable accounting framework, consolidation scope, policies, and formal review; a group total alone does not make a report final.
Financial data consolidation is the disciplined process of turning different financial representations of a business into one comparable, validated, and traceable view. The technology architecture can vary. The essentials do not: common financial meaning, controlled account mapping, entity and currency rules, intercompany reconciliation, visible exceptions, and accountable sign-off.
Explore Softype’s CFO resource page for related finance leadership topics, or begin with the Multi-Entity Consolidation Readiness Checklist.
Discuss financial consolidation and reporting with Softype. Bring your current entity pack, source-system inventory, or most difficult reconciliation to focus the discussion on the group figures leaders need to trust.
Helping businesses thrive with integrated ERP solutions.
NetSuite
Service
Company
Contact Us
Copyright © 2026


