TL;DR
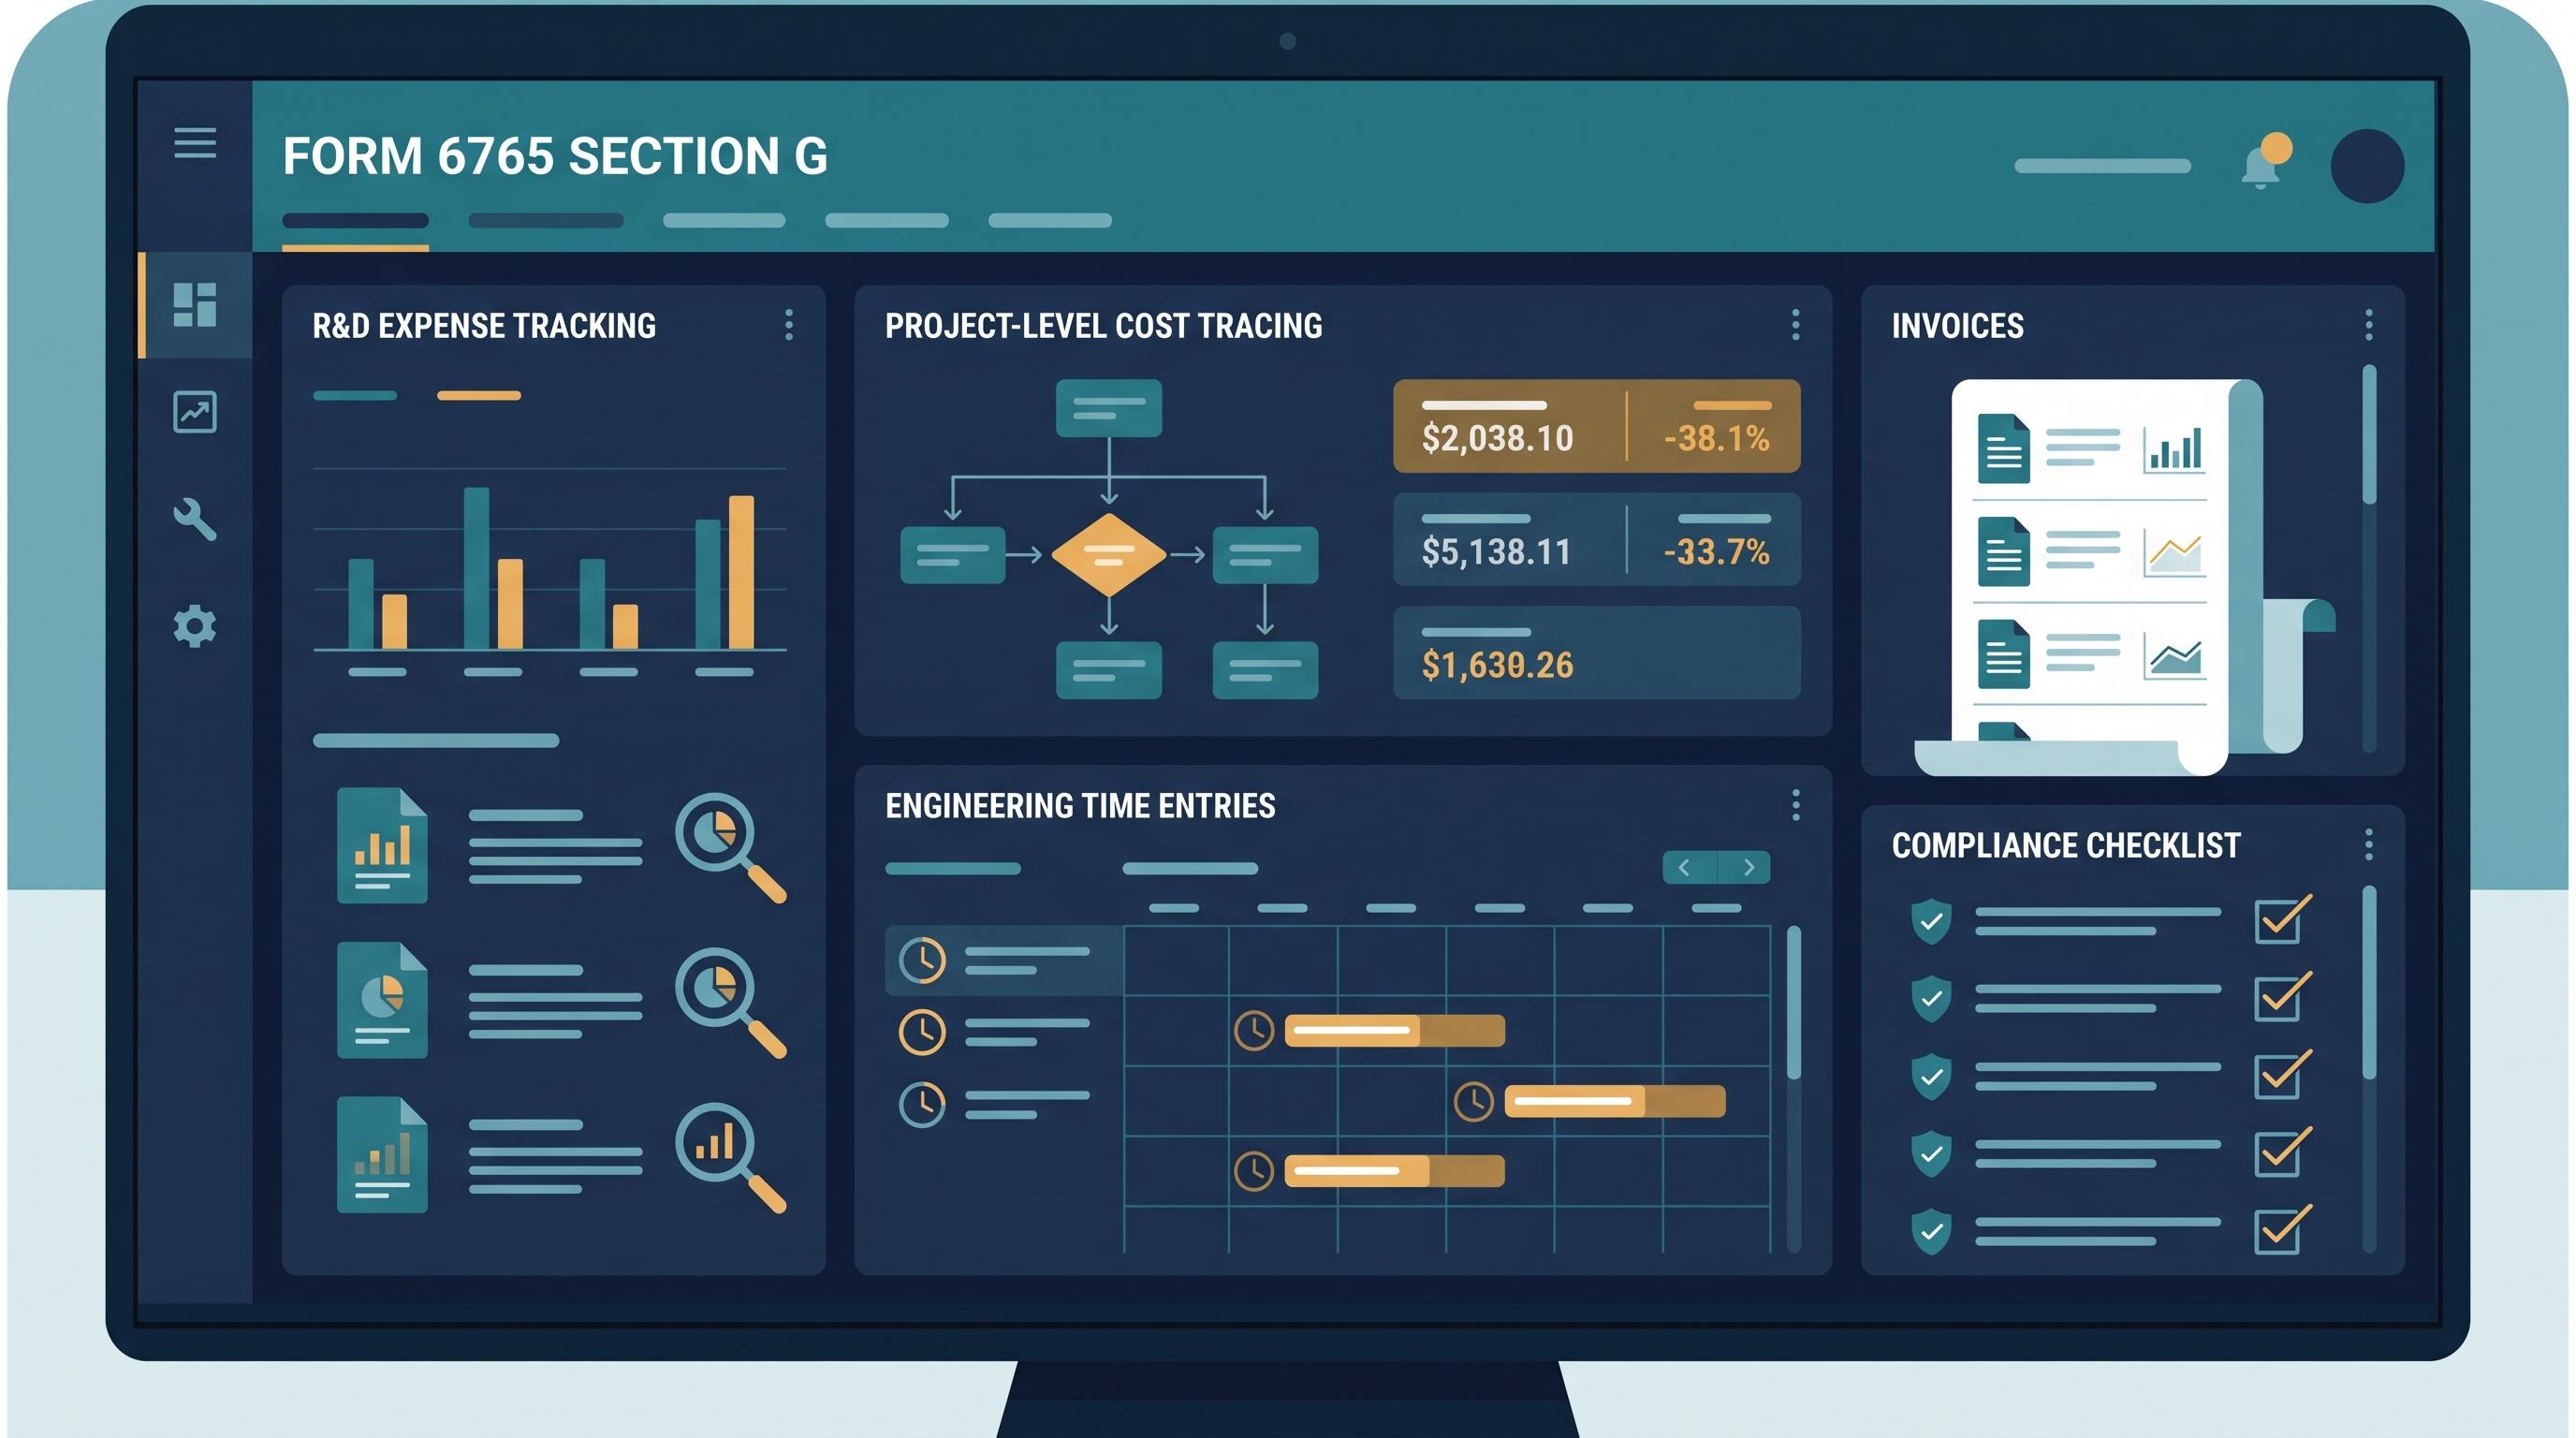
Form 6765 Section G now requires many taxpayers with tax years beginning after 2025 to report qualified research expenses (QREs) at the business-component level. To do that well, NetSuite should tie each component to time entries, purchasing, vendor bills, and technical support. It should also keep Section 174A treatment separate from Section 41 credit eligibility. The goal is simple: give your tax adviser a clean, traceable record instead of a year-end spreadsheet rebuild.
Finance teams need more than a total R&D spend number. They need to show which business component created each cost, what qualified activity it supported, and how the amount ties back to source records. Recent tax changes raised the reporting standard for the Section 41 credit. That makes component-level tracking an operating requirement, not a year-end cleanup project.
Many taxpayers with tax years starting after December 31, 2025, must complete Section G unless an exception applies. List business components from highest to lowest QREs. Continue until the listed components cover at least 80% of total QREs or you reach 50 components. The remaining components may be reported together. See the IRS Form 6765 instructions for the current rules and exceptions.
A business component is a product, process, computer software program, technique, formula, or invention held for sale, lease, license, or use in your trade or business. The analysis is not satisfied by labeling an entire engineering department “R&D.” You need to connect research activities and QREs to the specific component that generated them.
Some taxpayers may qualify for an exception. One possible original-return exception applies to a controlled group with total QREs of $1.5 million or less and average annual gross receipts of $50 million or less over the prior three tax years. Certain qualified small businesses claiming the payroll-tax credit may also qualify for an exception. These thresholds are not a reason to delay the data setup. Component-level records remain useful as your business grows, even if Section G does not apply yet.
Recent legislation added Section 174A. It generally restored immediate deduction for domestic research and experimental costs paid or incurred in tax years beginning after December 31, 2024. The law also created transition relief for some domestic costs capitalized from 2022 through 2024. Foreign research still follows a separate 15-year amortization rule. Review the IRS research credit guidance, IRS Section 174 guidance, and PwC’s H.R. 1 tax summary with your advisers.
The control point is to keep Section 174A and Section 41 distinct. Section 174A addresses the treatment of domestic research or experimental expenditures. Section 41 asks whether the research and cost meet credit-specific requirements. A domestic cost that is expensed under the Section 174 fix is not automatically a QRE.
Classification | Question answered | Suggested NetSuite field |
|---|---|---|
Book R&D | How is the cost presented financially? | Account, department, class, project |
Section 174A treatment | Is it domestic research, foreign research, elective amortization, or excluded? | Tax-treatment custom segment |
Section 41 treatment | Does it support qualified research? | Eligibility status and reason code |
Business component | Which product, process, software, or other component generated it? | R&D Business Component custom segment |
To support the Section 41 credit, test the research against four requirements for each business component. The research must have a permitted purpose. It must address technological uncertainty and include a process of experimentation. It must also be technological in nature. Statutory exclusions still apply. These include foreign research, funded research, work after commercial production, and routine testing. Customer-specific adaptation is also excluded, as is research in the social sciences, arts, or humanities.
Engineers should not have to make legal judgments in every time entry. NetSuite should capture the facts instead. Record the uncertainty, options considered, work performed, business component, people involved, and costs. Your tax adviser can use those facts to apply the legal standard. The IRS Section 41 audit guidance explains the records and links between costs and research that the Service reviews.
That evidence should sit on a stable business-component record, not only in a year-end tax study workbook. A component such as Automated Inspection Process, BC-2026-012 should state the technical information sought, the technical uncertainty, the hypothesis or alternatives tested, the owner, the activity dates, and links to specifications, test plans, tickets, prototypes, and results.

For a related view of how one governed financial data spine supports planning and analysis, see our NetSuite Planning and Budgeting guide.
Create an R&D Business Component custom record and an associated custom segment. Give each component an immutable ID, such as BC-2026-012, so it remains recognizable even if a project or product name changes. Use the segment on Projects, Project Tasks, time entries, purchase orders, vendor bills, expense reports, inventory issues, and journals where relevant.
Project is not always the same as business component. One project can cover several products or processes; conversely, one component may span multiple engineering workstreams. Use Projects as an operational container and the component segment as the Section G reporting key.
Information sought and the technical uncertainty
Technological basis and the experiments or alternatives considered
Business purpose research locations, and current status
Supporting evidence such as design specifications, source-control references, prototype results, test data, decision logs, and engineering tickets
A statement such as “improve the platform” is weak. A useful record explains the uncertainty: for example, whether a proposed allocation algorithm could meet a defined response-time and concurrency threshold while preserving data consistency. The objective is to capture contemporaneous operating evidence, not to turn project managers into tax counsel.
Wages are often the largest QRE category. Section G separately reports wages for direct research, direct supervision, and direct support. Configure time entry so employees working on R&D select the business component, project or task, activity classification, work location, and a concise description of the work performed.
Direct Research
Direct Supervision
Direct Support
Non-QRE R&D / Section 174A Only
Pending Tax Review
Section G calls for qualified supplies separately. Require the business-component code and QRE cost category on R&D-related purchase orders, vendor bills, expense reports, inventory issues, and requisitions. The record should distinguish a supply consumed in testing or prototyping from indirect overhead or general department spending.
Use exception reviews to identify research accounts, departments, suppliers, or projects with missing component tags. That turns the month-end close into a correction window rather than an after-the-fact reconstruction exercise.
For outside research, keep the master service agreement and statement of work with the related vendor bill or component record. Link the deliverables and proof of payment. Record where the research took place, who owns the results, and who bore the financial risk. Tag the vendor charge to the business component and the contract-research work type.
Keep the full accounting cost separate from the amount used for Section 41 review. Qualifying contract research is often included at 65%. Different rules may apply to qualified research consortium payments and some other arrangements. Do not use one percentage for every vendor. Have your tax team review the applicable amount.
If your team also needs stronger production and cost controls, read our NetSuite for Manufacturing implementation guide and NetSuite for Assembly Manufacturing guide for the operating model around work orders, costing, and shop floor data. Those controls make R&D tagging easier to govern once finance, operations, and engineering share the same process.
Month-end close and audit preparation are common trouble spots. Wage allocations, vendor costs, and project evidence may not roll up by business component. Then finance teams lose time, and leaders may question the results. The tax team may have to rebuild the support from payroll files, invoices, and interviews. Add component codes and activity types earlier. Review exceptions before filing season.
QRE category | NetSuite module or record | Fields and evidence to capture |
|---|---|---|
Wages | Projects, Project Tasks, Time Tracking, payroll reconciliation | Business Component ID; activity classification; task; hours; work description; location; employee role; approved wage-base reconciliation |
Supplies | Purchase Orders, Vendor Bills, Expense Reports, inventory issue or consumption records | Business Component ID; QRE cost category; item; quantity; consumption purpose; research location; invoice or receipt and testing evidence |
Contract research | Purchase Orders, Vendor Bills, vendor master, custom contract-research record | Business Component ID; vendor work type; gross amount; applicable Section 41 amount; research location; rights, funding, statement of work, invoices, and deliverables |
The biggest pain points usually show up in two places: month-end close and audit prep. Finance teams lose time when wage allocations, vendor costs, and project evidence do not roll up cleanly by business component. Leaders lose confidence when the tax team has to rebuild support from payroll exports, invoices, and interviews. If that is happening now, add the component code, activity classification, and exception reviews earlier in the process rather than waiting for filing season.
QuickBooks can store accounting transactions. Excel can assemble a calculation. The challenge is linking each cost to a business component, qualifying activity, source document, and supporting evidence. When project IDs, time entries, vendor terms, and technical records sit in separate systems, teams must join the data by hand. They may also need to rely on interviews after the work is done.
Using NetSuite does not automatically make your records audit-ready. The benefit comes from building good controls into daily work. Capture the business-component tag, activity type, approval, attachments, and exceptions as work happens. Projects, Time Tracking, Accounts Payable, custom fields, and saved searches can link Section G reports to source transactions and evidence.
Create or update business-component records as initiatives begin, change, commercialize, or close.
Require component, activity classification, and meaningful work descriptions on R&D time entries.
Review and approve time before payroll and period close.
Tag R&D-related purchasing, AP, expense, and inventory transactions at line level.
Attach or link technical evidence, contracts, invoices, and deliverables to the related component.
Run exception reviews for missing tags, pending tax review, foreign work, unapproved time, and vendor charges without supporting agreements.
Produce a monthly Section 41 register and reconcile it to payroll, AP, project costing, and the general ledger.
Identify the business component. Assign a stable ID, name, component type, legal entity, and owner.
Document the four-part-test facts. Record permitted purpose, technical uncertainty, technological basis, and experimentation evidence.
Code employee time. Capture component, task, activity classification, location, and work description, and retain approval history.
Reconcile wage data. Connect approved time allocations to the appropriate wage base and separate direct research, supervision, and support.
Tag supply transactions. Preserve component, cost category, item, amount, consumption purpose, and source documents.
Validate contract research. Retain the agreement, statement of work, rights and funding terms, domestic-location evidence, invoices, deliverables, and reviewed applicable amount.
Separate Section 174A and Section 41. Retain distinct tax-treatment fields and exclusion reason codes.
Build the Section G output. Rank total QREs by component, identify the 80% or Top 50 population, and reconcile the register to the relevant Form 6765 totals.
If you want to pressure-test your current setup before year-end, book a 30-min R&D expense tracking scoping call with Softype. We can help your team map the component, time, AP, and documentation controls needed for a cleaner Section G workflow.
Section G makes business-component tracking the core reporting unit for many 2026 filings.
Keep Section 174A treatment separate from Section 41 credit eligibility in your ERP design.
Tag wages, supplies, and contract research to a stable component code at the transaction level.
Store technical uncertainty, experiments, and source evidence with the component record, not in a year-end workbook.
Build a monthly Section G register so tax review starts from governed records instead of spreadsheet reconstruction.
NetSuite can support the workflow when Projects, Time Tracking, AP, and custom segments are configured to capture the right evidence as work happens.
Softype is an Oracle NetSuite solution provider with more than 25 years of experience and over 600 implementations. We help finance and tax teams design the business-component, time, AP, and documentation controls that make Form 6765 Section G tracking cleaner and more defensible so the tax team can pull a controlled monthly register instead of rebuilding the year from payroll files, invoices, and interviews.
If you want to pressure-test your current setup before year-end, we can walk through the component, time, purchasing, and evidence controls needed for a more reliable Section G workflow. Book a short scoping conversation or get in touch when you are ready.
This article provides general ERP-configuration information, not tax, legal, or accounting advice. Consult qualified advisers on Section 41 eligibility, Section 174 and 174A treatment, elections, controlled-group rules, and Form 6765 filing positions.
OBBBA added Section 174A and generally restored immediate deduction for domestic research and experimental expenditures paid or incurred in tax years beginning after 2024, with elections and transition mechanisms affecting prior capitalization. It did not remove the separate Section 41 credit analysis or the need for component-level evidence.
Potential recovery and transition options exist for domestic costs capitalized during those years, but the available treatment depends on your facts, timing, and applicable provisions. Confirm the proper approach with your tax adviser rather than changing historical accounting records based on a general article.
Section G is the business-component information section of Form 6765. For taxpayers required to complete it, it reports identifying and QRE information for the components that make up the required portion of total QREs, subject to the form’s 80% or Top 50 framework and exceptions.
Use Projects and Project Tasks for operating work, then apply a stable R&D Business Component custom segment to time entries and transaction lines. That allows multiple projects or tasks to roll into one tax-reporting component while retaining the underlying detail.
Yes. Approved, contemporaneous time entries can provide a strong operating record for allocating work by component and activity type. Your tax team should still reconcile those allocations to the appropriate wage base and determine the final Section 41 treatment.
Maintain a concise component-level narrative that identifies the technical question, alternatives considered, experiments performed, and results, then link the record to existing specifications, test plans, tickets, prototype evidence, and technical decision documentation.
The issue is not the brand of accounting system. It is whether you can substantiate the connection between costs, qualified activities, and business components. A QuickBooks-and-spreadsheet process can be supported by strong records, but disconnected and retrospective data collection is harder to govern and reconcile than a structured ERP workflow.
No. NetSuite should capture the component, activity, transaction, and evidence trail your tax adviser needs. Final eligibility, elections, controlled-group treatment, and filing positions remain fact-specific tax decisions.
Helping businesses thrive with integrated ERP solutions.
NetSuite
Service
Company
Contact Us
Copyright © 2026


