A month-end report can be accurate and still arrive too late to protect a project’s margin. Before managers approve labor, post invoices and certify subcontractor billings, crews may already have used the remaining budget. Project cost management must look beyond costs the accounting team has recorded. Leaders also need to see committed spend, work left and the latest estimate of final cost.
Answer: Project cost management is the ongoing process of comparing an authorized project budget with actual costs, open commitments and a current forecast of the work still required. Reviewing these separately helps contractors detect budget variance earlier, understand what is driving it and decide whether delivery, procurement, scope or schedule action is warranted. A forecast signals risk; it does not guarantee that every variance can be recovered.
For a broader look at construction job-costing practices, start with NetSuite for Construction: Project Tracking & Job Costing ERP.
Posted actuals answer what has been recorded through a cutoff date. They do not necessarily capture labor already performed but not approved, goods received but not invoiced, subcontract work awaiting certification, or obligations created by an open purchase order.
Keep these cost views separate. Actual cost covers work the team has incurred and recorded. Committed cost covers obligations the contractor has made, such as an open purchase order or subcontract balance, that have not yet reached the invoice or posting stage. Estimate to complete (ETC) forecasts the cost to finish the remaining work, including work the team has not committed yet. Estimate at completion (EAC) adds actual cost and ETC. Use consistent figures so you do not count any cost twice.
For a standard terminology reference, see the PMI Lexicon of Project Management Terms (2026), which defines actual cost as realized cost incurred for work performed.
To find budget remaining, subtract recorded costs from the budget. That number does not tell you what it will cost to finish the job. Finance still needs a project budget vs actual report for accounting. Active cost control adds open commitments, costs the team has not posted yet, remaining work and the latest forecast.
Actual spend — Month-end review: Finance sees transactions posted by cutoff. Active control: Finance checks current actuals, cutoff gaps and accruals.
Committed costs — Month-end review: The report may omit open commitments from actuals. Active control: Project teams track open purchase orders, subcontracts and other obligations separately.
Estimate to complete — Month-end review: Teams may mistake unused budget for the cost to finish. Active control: Teams rebuild ETC from remaining quantities, hours and known risks.
Variance visibility — Month-end review: Finance reports variance already booked. Active control: The team forecasts final cost and tracks variance by cost code.
Change-order status — Month-end review: Teams add approved changes after they process them. Active control: Teams separate approved changes from pending exposure.
Ability to intervene — Month-end review: A late report can leave the team with few choices. Active control: Current forecasts help teams act sooner on procurement, staffing, scope and schedule.
For construction developers managing project cost, WIP and change orders, Softype’s ERP for Real Estate page provides a related view of those capabilities in a real-estate development setting.
Illustrative figures only. A contractor has a ₱10.00 million contract and an ₱8.00 million cost budget. At cutoff, posted actuals are ₱5.00 million, so a ledger-only view suggests ₱3.00 million remains.
Remaining exposure | Amount | Cost treatment |
|---|---|---|
Open subcontractor commitments | ₱1.20M | Uninvoiced contracted balance |
Materials ordered | ₱0.60M | Open purchase obligations |
Equipment still required | ₱0.25M | Forecast cost beyond commitments |
Additional labor to finish | ₱1.40M | Forecast remaining work |
Pending scope-change cost | ₱0.30M | Probable exposure shown separately |
Total remaining exposure | ₱3.75M | Commitments and other ETC, without duplication |
When these amounts do not overlap, add ₱5.00M in actuals to ₱3.75M in ETC. The EAC is ₱8.75M, or ₱750,000 above budget. If contract revenue stays at ₱10.00M, forecast profit falls from ₱2.00M to ₱1.25M. This example does not count any pending recovery. Accounting has not recorded an overrun yet, but the forecast already signals one.
PMI’s article on earned-value forecasting of final cost discusses using forecasts alongside the project manager’s reported position to assess expected completion cost.
Reconcile commitments as invoices and receipts post. Do not add a subcontract’s full value on top of invoices already recorded against it. The goal is a complete outlook, not an inflated total.
Commitment tracking moves visibility closer to the decision that created the obligation. A materials code with a ₱1.00 million budget and ₱400,000 in posted bills appears to have ₱600,000 available. If open purchase orders total another ₱500,000, only ₱100,000 remains uncommitted before further requirements, freight or price changes.
Review purchase orders, subcontract awards, rentals and approved changes by project and cost code. For each one, compare the original amount with approved changes, invoices, receipts, cancellations and the open balance. Requisitions may warn of future spending, but each company decides whether to count them as commitments. Also list needed work that procurement has not awarded yet. That work may still add cost, even without a signed order.
Oracle NetSuite’s Project Profitability Report documentation separately lists incurred and committed project costs, illustrating why these views should not be collapsed.
For a construction-specific view of project tracking and job costing, see the NetSuite construction job-costing guide.
Build ETC from the latest work plan, not by simply subtracting actual costs from the budget. Use one shared date for the review. Then estimate the cost of the labor, materials, subcontractors, equipment, overhead and closeout work still to come. Break the estimate down by cost code.
AACE International’s Recommended Practice 80R-13 on Estimate at Completion describes EAC as a periodic appraisal of project status and remaining work to estimate total cost at completion.
For labor, compare planned hours, hours consumed and current hours remaining by role. Productivity, overtime, crew mix, rework or a delayed finish may change the forecast before payroll posts. As an illustration, 1,000 planned hours at ₱1,000 each cost ₱1.00M; a revised need of 1,300 hours at ₱1,100 is ₱1.43M. That ₱430,000 movement is forecast exposure, not posted actual cost.
For materials, separate quantity from price. Freight, duties, damage, substitutions, expediting and supplier price changes can alter expected landed cost. Track the latest expected quantity and unit price, not just early invoices; the first deliveries may not represent the full buy.
Certified progress billings can lag subcontractor exposure. Review the original agreement, approved changes, pending claims, work performed but not billed, remaining value and expected final amount separately. Do not treat a pending claim as settled fact, but do not ignore credible cost exposure until it appears on an invoice.
Equipment cost depends on usage and duration. Rental extensions, fuel, operators, standby and mobilization may change when access, weather or sequencing moves the schedule. Connect the latest completion date to time-dependent cost codes and assess owned-equipment charges consistently too.
A scope change can add cost before the customer approves a price. Track each change as identified, submitted, approved, rejected or disputed. Add likely costs to the forecast under your company’s rules, but show possible revenue separately. Do not treat it as approved or certain. Add approved changes to the current budget; keep unapproved work visible as a risk.
For the accounting treatment of scope and price changes, consult the IFRS 15 standard; a pending commercial request should not be presented as approved revenue.
Finance and project managers should use the best current cost forecast in WIP reports while keeping the original budget visible. Finance checks posting dates, missing costs, cost codes and reporting rules. Project managers check progress, work left and site conditions. When their views differ, document the reason, who will resolve it and by when. Do not hide uncertainty by averaging the estimates.
Cost codes connect the estimate, budget, commitments, actuals and forecast. A total-project variance tells leaders little about whether the driver is labor productivity, material price, a subcontract package or rental duration. Consistent codes let the team investigate a cause and assign an owner, making job cost control practical at the work-package level.
Choose cost codes that show which part of the job is driving a cost change, but keep them simple enough for teams to use correctly. Use the same codes for estimates, timesheets, purchase orders, receipts, invoices and forecasts. Check uncoded or misclassified costs before reviewing trends. Compare the current budget with actual costs, unposted costs, open commitments, remaining-work estimates and forecast final cost. This makes project cost tracking and forecasting clearer: the team can see what has posted, what it owes and what it expects to spend.
For a construction-specific explanation of how cost codes support budgeting, tracking and reporting, see Procore’s construction cost-code guide.
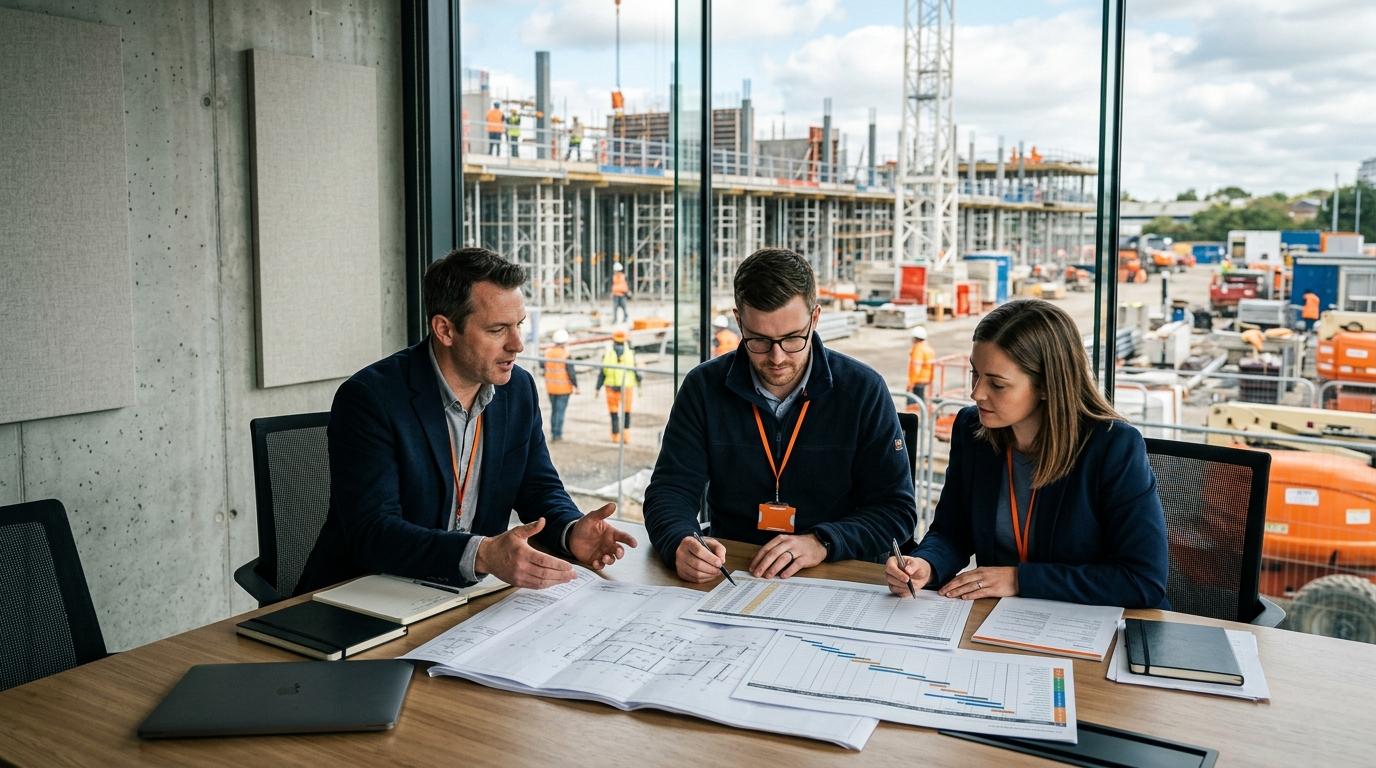
Project managers know the work, the crew’s progress, site conditions and schedule limits. Finance checks recorded costs, open commitments, missing costs and forecast rules. In a shared review, the teams reconcile actuals, update commitments, confirm progress, rebuild ETC and calculate EAC. They explain what changed since the last forecast and assign each decision an owner and due date.
The right response depends on why costs changed. A team may adjust the work sequence, review staffing, address supplier problems, measure the cost of a delay, raise a change order or update the forecast. Faster work can cost more. A new supplier may affect quality or timing. Weigh the trade-offs; do not assume every cost increase can be recovered. If a higher cost is likely, update the forecast.
Construction project margin can also move because of scope, supplier conditions, site access or timing; it is not automatically evidence of poor project management. State the driver and evidence so leaders can choose an appropriate response rather than blame a team for a result outside its control.
Confirm the original budget, approved changes and revised budget by cost code.
Reconcile actual costs, cutoff, accruals, receipts, time and uncoded transactions.
Validate open purchase orders, subcontractor commitments and equipment spend net of invoices, receipts and cancellations.
Review labor and material trends, subcontractor spend, quantities, rates, productivity and schedule-driven costs.
Separate approved and pending changes; quantify any work proceeding at risk.
Update ETC from current remaining hours, quantities, commitments, risks and closeout needs.
Calculate forecast final cost (EAC) and compare it with the original and revised budget and the previous forecast.
Assign each material variance a cause, owner, action and follow-up date.
It is the recurring practice of planning, recording and forecasting project cost while work is underway. It compares actuals, commitments and remaining-work estimates with the authorized budget so managers can investigate movement and decide on action.
Actual-cost reports show only costs the team has recorded so far. They may leave out open orders, unbilled work and the cost to finish remaining scope. A project can look within budget today even when the latest EAC points to an overrun.
Committed costs are obligations for future expenditure, such as the open balance of an awarded subcontract or purchase order. Track them separately from posted actuals and reduce them as invoices, receipts, cancellations or other changes alter the balance.
ETC is a current estimate of the cost to finish remaining work, based on quantities, labor hours, rates, procurement, schedule and credible exposure. It should not default to budget less actuals unless the original remaining-work assumptions still hold.
Show approved changes in the revised budget and pending, rejected or disputed changes separately with expected cost, commercial status and an owner. For each material variance, document the cause, forecast impact, decision and next review date.
Review volatile cost drivers, labor, procurement and changes weekly on active jobs, with a formal monthly reconciliation of actuals, commitments and forecasts. Increase the cadence when major buyouts, schedule changes or work at risk make exposure move quickly.
When job costing, purchasing, time, subcontract and budget information use consistent project and cost-code references, teams can compare actuals and commitments with a current forecast more easily. Timely entries and disciplined ETC reviews remain essential; software alone does not guarantee an early warning.
For a related perspective on profitability in services businesses—not a replacement for construction job-cost control—read Project Profitability by Client and Service: What Revenue Reporting Hides.
Discuss project cost control and margin visibility with Softype.
Helping businesses thrive with integrated ERP solutions.
NetSuite
Service
Company
Contact Us
Copyright © 2026


