A school can bill enough tuition to support its annual operating budget and still face a cash gap before payroll or supplier payments. For the CFO, controller, finance director, or bursar, the risk is timing: payment plans, overdue balances, and unsettled receipts can leave the forecast short even when billed totals look healthy. Softype’s ERP for Education covers broader education workflows; this article focuses on tracing tuition into cash and budget decisions.
School finance operations work best when leaders can trace tuition from enrollment and fee schedules through student accounts, receipts, reconciliation, cash forecasting, and budget-to-actual review. Billed tuition, outstanding receivables, collected cash, and recognized revenue are related, but they are not interchangeable; accounting and aid treatment varies by institution and jurisdiction.
School finance operations connect the decisions that determine what students owe with the evidence that shows what the institution can plan to spend. For a CFO, controller, finance director, or bursar, this means more than producing invoices or closing the ledger. The process must carry the right enrollment, fee, payment, and collection information forward in a usable form.
The tuition-to-cash path can be viewed as a sequence: enrollment assumptions determine the student population; approved fee schedules establish charges; scholarships and discounts change the family obligation; payment plans assign due dates; receipts reduce balances; settlement and reconciliation confirm the cash; and finance reporting updates forecasts and budget variance analysis. A break in any handoff can make a later report incomplete or difficult to explain.
Keep four measures distinct. Billed tuition is assessed to student accounts. Student receivables are outstanding balances, whether due now or later. Collected cash is money received, with settlement status considered before it is treated as available. Recognized revenue follows the institution’s accounting policies. They answer different questions, so no one number should stand in for all four.
Enrollment is a revenue and cash-flow assumption, so finance leaders need to know which student count supports each forecast. Applications, offers, paid deposits, registered students, billed accounts, and students still enrolled after withdrawal periods are not interchangeable. Define the count and cut-off date used for planning, then update expected charges and receipts when registrations, withdrawals, or program changes affect student accounts.
When enrollment differs from plan, finance should quantify the resulting change in net tuition assumptions and the expected months of collection—not just report a headcount variance. Program changes, withdrawals, and late registrations can alter both charges and timing. NAIS notes that enrollment is the largest revenue generator and staffing the largest expense generator for a typical independent school.
Fee schedules determine whether student receivables and tuition forecasts start from the right charges. Rates may differ by program, year level, course load, campus, or term; finance should be able to see which approved schedule and effective date applied to each account. Record scholarship approvals and later adjustments with their rationale and authorization so the controller can explain billing variances and protect the audit trail.
Payment plans determine when expected tuition can become cash. A family paying in full before term, by semester, or monthly may owe the same annual amount but create a different cash profile. Finance should compare installments due with actual collection patterns, then update the forecast when plan mix or payment behavior shifts; billed totals alone cannot show whether cash will cover near-term obligations.
Financial aid and discounts change the expected family obligation, while external awards can have separate approval and payment timing. For the finance director, the key is to distinguish approved institutional reductions from confirmed third-party funding and pending support; pending approval is not settled cash. Apply the institution’s accounting policies when presenting these amounts. For independent schools, NBOA describes net tuition revenue as a more useful planning measure than gross tuition alone when tuition discounts are considered.
Late payments also change timing and risk. A balance not yet due is unlike one that has aged for several months, is disputed, or has no active arrangement. Aging bands help prioritize follow-up and provide a basis for revising expected collection dates. They should inform the cash forecast without automatically treating every overdue balance as either immediately collectible or permanently lost.
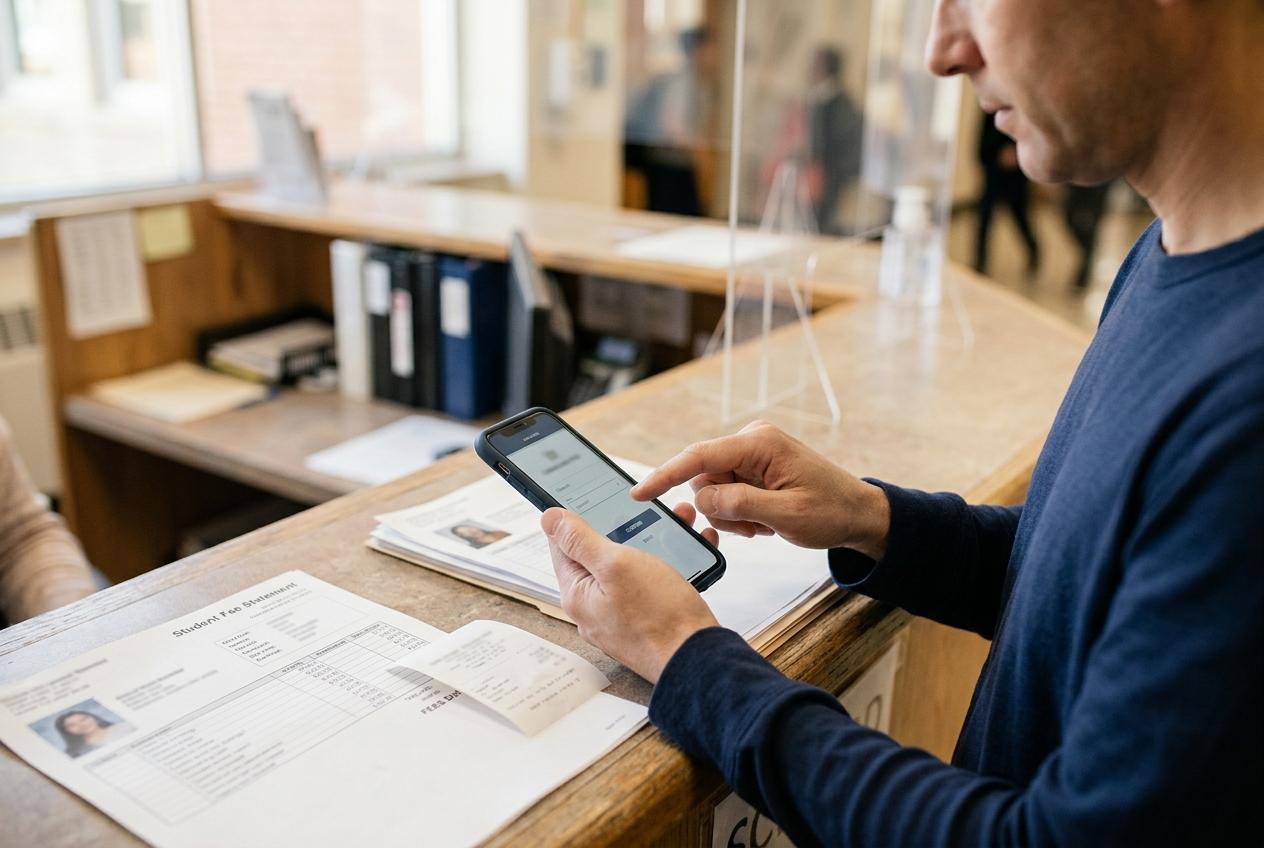
Tuition collection is not complete when a payment appears in a portal; it is complete when the receipt, student balance, settlement, and accounting entry can be explained together. A family payment may arrive by bank transfer, card, cheque, cash, or payment service. Finance needs enough information to identify the payer, student, charge, amount, date, and channel, then apply the payment correctly.
The next handoff is reconciliation. Finance should match payment activity with provider settlement and bank deposits, account for fees, and investigate reversals, refunds, duplicate entries, chargebacks, or unidentified deposits. A payment may reduce a student balance before funds settle, while an unallocated bank transfer may increase cash without clearing the student’s overdue status. Those differences need to remain visible until resolved.
From there, student receivables activity should reconcile with the relevant general-ledger balances on a defined cadence. The process should preserve an audit trail for adjustments and identify unresolved items by age, owner, and next action. Specific control obligations vary, but a forecast built on unreconciled collections is less dependable because the cash evidence itself is uncertain. For institutions participating in applicable U.S. federal student-aid programs, the U.S. Department of Education sets requirements for auditable records, fund accountability, budget comparisons, and specified student-level reconciliations; those requirements do not apply universally to every school.
For the controller or bursar, each handoff needs a named owner, cutoff, and exception path: who confirms enrollment changes, approves fee or aid adjustments, posts receipts, resolves unmatched deposits, and updates the forecast. Separate student, billing, payment, accounting, and planning tools can support the process, but finance must be able to reconcile their outputs and explain differences without relying on undocumented spreadsheet fixes.
The practical difference is whether finance can explain the path from the student charge to the planning decision without rebuilding it manually. A connected process does not require every function to sit in one application. It requires reliable information to move between the relevant workflows.
Finance area | Disconnected billing and finance | Connected school finance operations |
|---|---|---|
Billed tuition visibility | Charges, aid, and enrollment changes are combined from separate files. | Fee schedule, enrollment status, adjustments, and student charges can be traced. |
Collections tracking | Cash totals and student balances update on different schedules. | Due, paid, overdue, and future installments are distinct in reporting. |
Reconciliation | Deposits are manually matched after reports are prepared. | Receipts, account postings, settlements, and ledger activity are linked, with exceptions identified. |
Cash forecasting | Annual tuition is spread across periods with limited timing evidence. | Due dates, collection patterns, overdue recovery, and settlement timing inform expected inflows. |
Budget-to-actual review | A variance has no clear explanation from enrollment to receipt. | Enrollment, aid, billing, collections, and current outlook can be reviewed against plan. |
Finance workload | Staff re-key, consolidate, and check totals across exports. | Staff focus more on exceptions, reconciliations, and explaining variances. |
The aim is not a dashboard for its own sake. Leaders should be able to move from an institution-wide figure to the underlying student-account or reconciliation issue, subject to appropriate privacy controls. Clear definitions also matter: teams need to agree on what billed, due, collected, settled, and forecast mean. Softype’s ERP for Education describes the broader education-administration context for connected finance workflows.
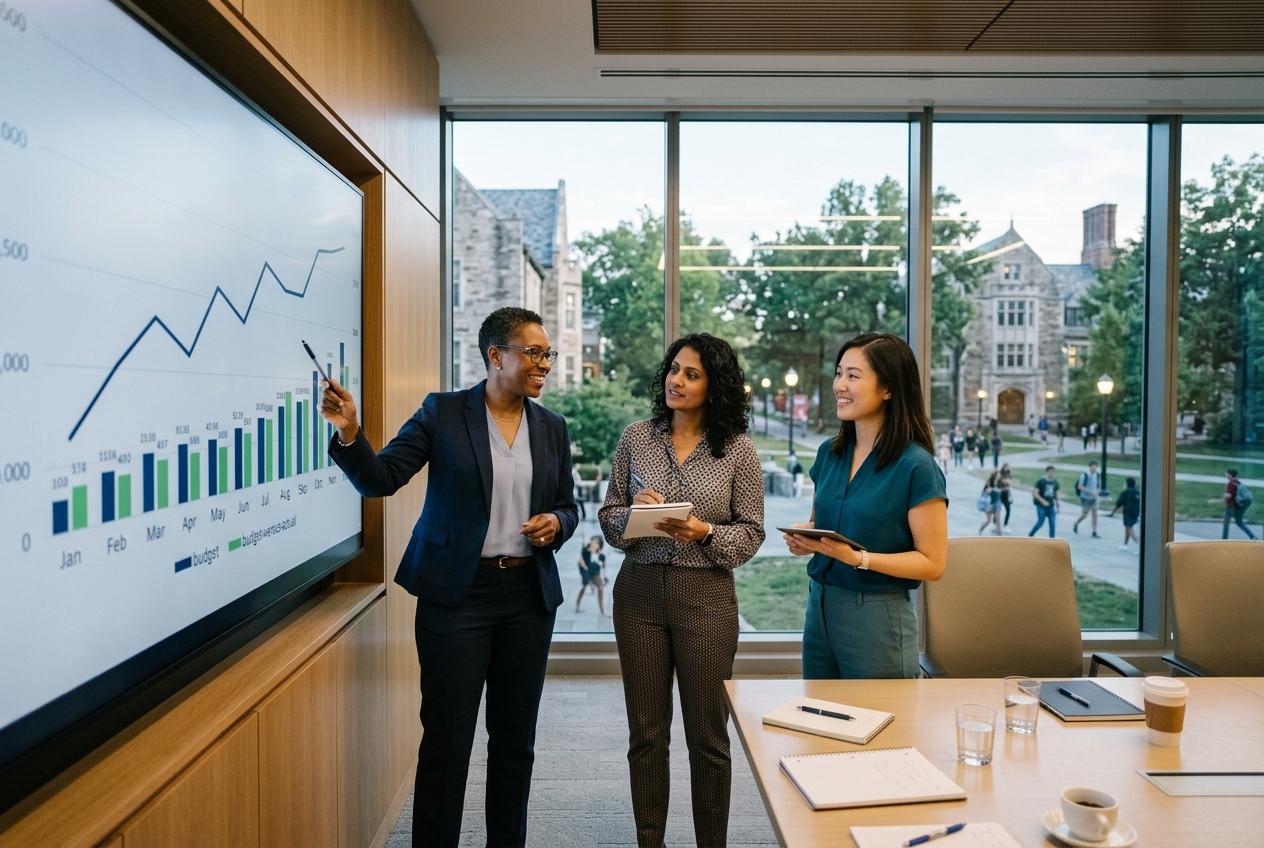
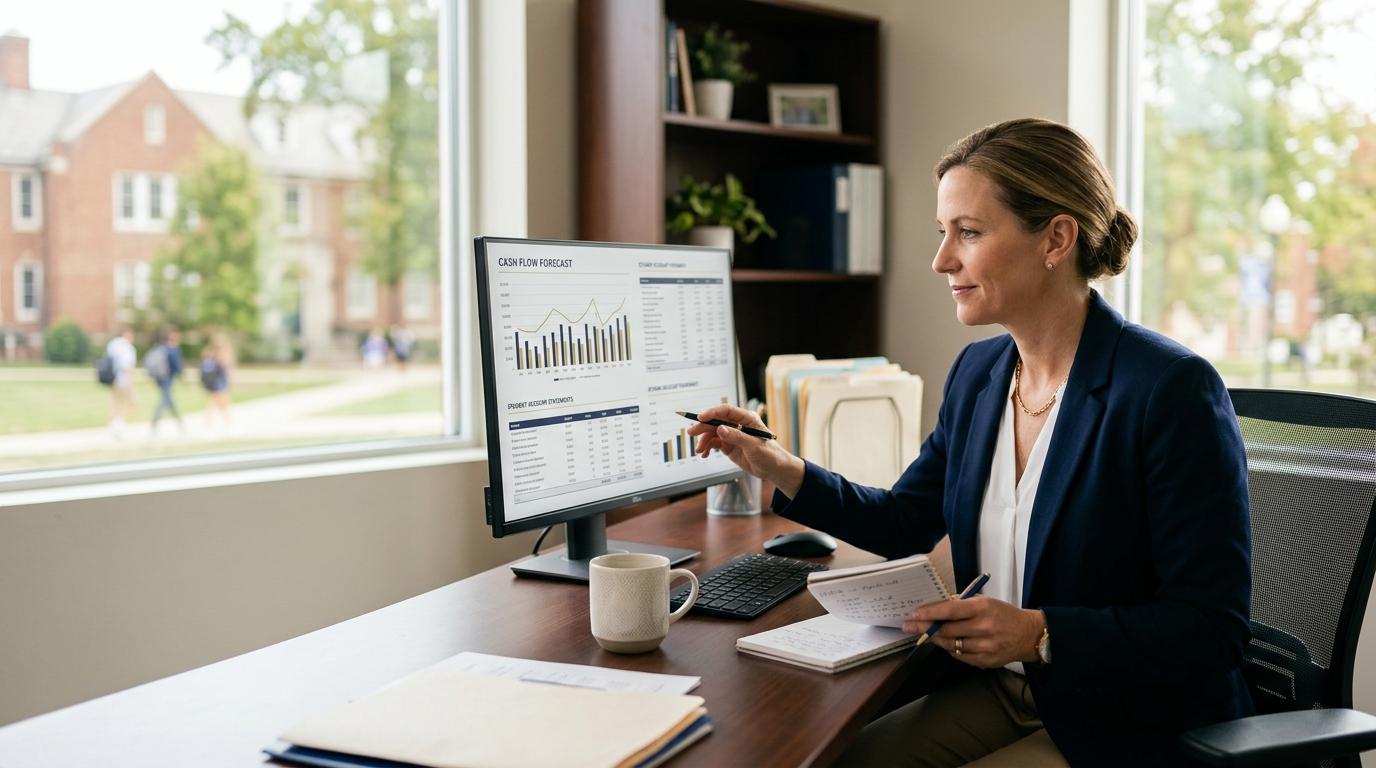
A useful school cash flow forecast answers when cash is expected, not only how much tuition is planned for the year. Begin with reconciled opening cash, schedule expected receipts by week or month, and compare them with payroll, suppliers, facilities, refunds, and other expected obligations. Carry the projected closing balance forward and refresh it as actual activity replaces assumptions. NBOA’s long-range financial model includes scenario comparisons and a cash-flow forecasting module for independent schools.
For tuition inflows, separate amounts by confidence. Settled receipts and confirmed payments with known dates are different from current installments expected based on historical behavior. Overdue recoveries, pending aid, disputed balances, or uncertain sponsor payments should be identified as at-risk or contingent rather than blended into the base case as certain.
Consider an illustrative example: ₱12 million in tuition installments is due this month, but recent collection patterns suggest ₱9.5 million will settle in the period, with ₱1 million of older receivables expected to be recovered. The base forecast includes ₱10.5 million in tuition receipts, not the full ₱12 million billed or due. If projected cash is tight before payroll and suppliers, leaders can review assumptions and timing while there is still room to act. The figures are examples, not a benchmark.
Keep the approved budget as the baseline. The latest forecast answers a different question: based on current enrollment, aid, billing, collection timing, and expenses, where might the year end? A cash shortfall does not automatically mean a revenue shortfall. It may reflect delayed payments, lower enrollment, higher aid, billing errors, refunds, or weaker collectability; each cause has a different planning implication.
In a monthly budget-to-actual review, compare expected and collected tuition, receivable aging, cash outlook, and operating-budget variances. Explain material differences and assign an owner, impact, and next action. If the issue is timing, cash may move between periods; if enrollment or net tuition assumptions have changed, the year-end forecast may need revision. Departmental allocations are more useful when leaders also know what is spent, what is committed, and what funds remain available under their policies. NBOA practitioner guidance on monthly school reporting recommends reviewing budget performance and updating year-end projections as information develops.
If campus coordination is the central challenge behind your finance handoffs, read Multi-Campus School Operations: When Spreadsheets Stop Being Enough. Its focus is shared visibility and consistent processes across locations; this article stays focused on tuition-to-cash planning.
Finance leaders should be able to trace tuition from a student account through collection and into the latest plan. Use this checklist to test where information changes hands or loses context:
Fee schedules: Can the team identify the approved rate, applicable fees, effective period, and authorized exceptions for each student?
Enrollment assumptions: Does the tuition forecast reconcile to a defined student population and account for registrations, withdrawals, transfers, or program changes?
Payment plans: Are installment amounts, due dates, payer details, and approved plan changes visible?
Scholarships or discounts: Are awards and reductions approved, categorized by funding source, and separated from cash received?
Receipts: Can each payment be traced to the student, charge, payment channel, date, and account posting?
Overdue balances: Can teams distinguish not-yet-due, overdue, disputed, and arranged balances and assign follow-up?
Reconciliation timing: Are settlements, bank deposits, student accounts, and ledger balances reconciled on a defined cadence, with exceptions tracked to resolution?
Forecast updates: Do actual receipt patterns and upcoming obligations refresh the cash forecast during the academic year?
Budget variances: Can leaders explain differences by enrollment, aid, billing, collection timing, or other causes while preserving the approved budget baseline?
If several answers depend on manual consolidation, start with the handoff that most affects the next cash decision. A traceable student account is the beginning; an explainable forecast and timely budget review are the outcome.
School finance operations connect revenue and spending workflows to financial control and planning. For tuition, this includes enrollment assumptions, fee assessment, student billing, collections, receivables, reconciliation, cash forecasting, and budget review.
Use consistent student and charge identifiers across billing, receipts, and accounting. Compare billed and due amounts with reconciled collections, then update the cash forecast and explain material changes in the latest budget outlook while keeping the approved budget as a separate baseline.
Billed tuition is a charge assessed to a student account. Collected cash is payment received, and settlement should be checked before treating it as available bank funds. Neither figure automatically equals recognized revenue, which follows the institution’s accounting policy.
Schedule receipts using actual payment plans and expected collection timing, add other inflows, and compare them period by period with payroll and other obligations. Refresh the forecast as enrollment, overdue balances, aid timing, refunds, and receipts change.
Use receivables aging with account notes, dispute status, and approved payment arrangements. Separate amounts not yet due from delinquent balances and follow a consistent process; escalation and any effect on student status should follow school policy and applicable law.
It helps leaders distinguish delayed cash from changes in expected tuition or collection risk. Finance can update near-term liquidity expectations and review spending commitments earlier instead of waiting for a year-end variance report.
No. Separate student, billing, payment, accounting, and planning systems can work when data ownership, identifiers, controls, and reconciliation responsibilities are clear. The test is whether staff can trace a material variance without manually rebuilding the full transaction chain.
Discuss school finance and tuition visibility with Softype.
Helping businesses thrive with integrated ERP solutions.
NetSuite
Service
Company
Contact Us
Copyright © 2026


