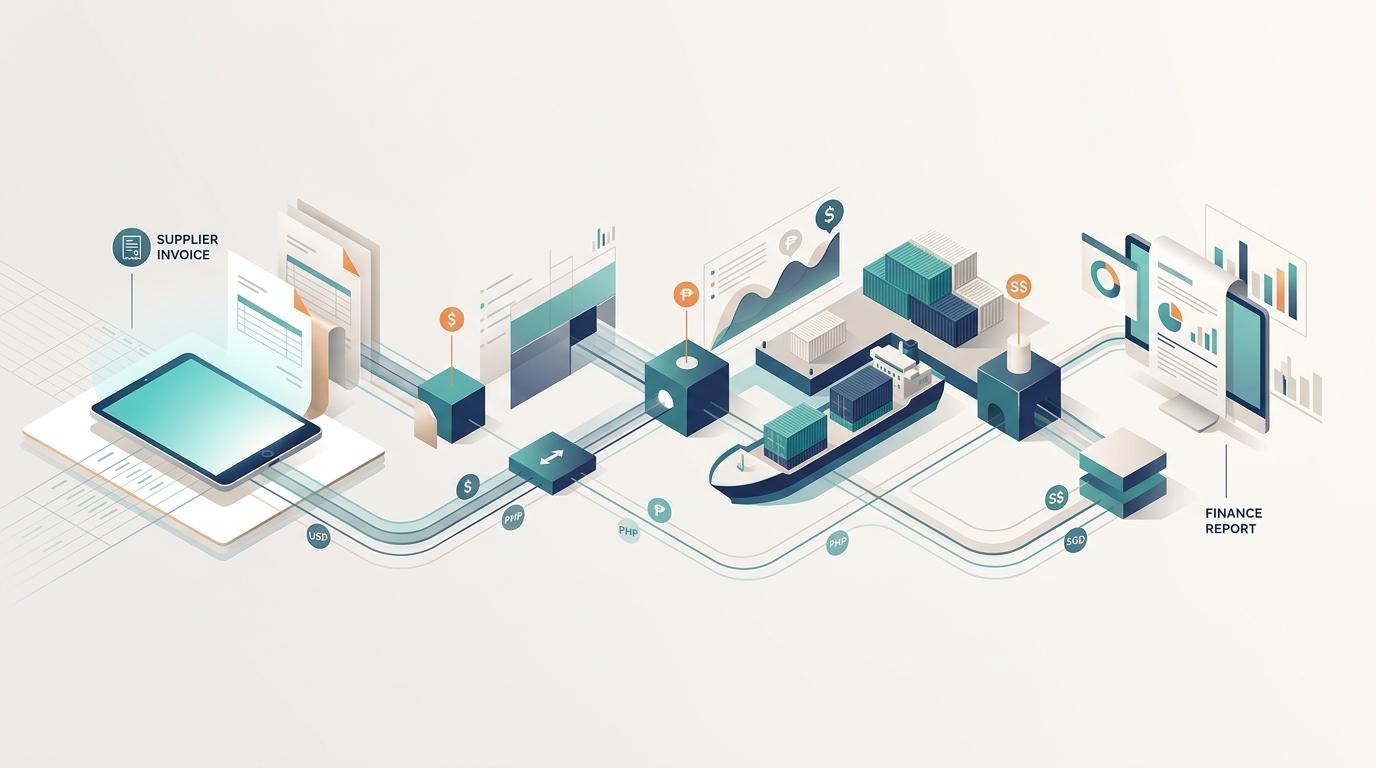
A supplier quotes USD 50,000. A Philippine distributor reviews the purchase against a peso budget. The goods arrive weeks later, and the supplier is paid after the dollar has moved. Freight and handling charges come in separate bills. Sales may then invoice a Singapore customer in SGD. One purchase now involves several currencies, dates, teams, and cost updates.
This is the daily challenge of multi-currency management for trading companies. Separate spreadsheets can track parts of the process, but they rarely stay aligned as rates and costs change. Purchasing, payables, pricing, and reporting can end up with different views of the same deal.
Start with Softype’s ERP readiness assessment to identify the handoffs that create the most rework.
Multi-currency management means keeping the original currency and amount for each purchase and sale, while recording the rate basis and date used. Finance reviews open foreign-currency balances as rates change, and separates FX movement from product margin. A connected workflow helps staff trace a transaction from supplier quote to payment and reporting. Foreign-currency activity alone does not mean a company needs multiple legal entities.
The supplier’s USD quote is not automatically the peso value first recorded in the books or the peso amount eventually paid. Procurement may use a planning rate to judge affordability. Finance may use a transaction-date rate for accounting, a closing rate for open balances at period-end, and a settlement rate when the bill is paid. These rates answer different questions.
Keep three terms separate. Transaction currency is the currency on a supplier bill or customer invoice. Entity base currency is the currency used for that entity’s books; the entity’s functional currency is set under its accounting policy. Group reporting currency is the currency used to present results across entities. Recording a USD bill in one entity’s PHP books is different from translating another entity’s financial statements for a group report.
Under IAS 21, a foreign-currency transaction is first recorded in the functional currency using the spot rate on its transaction date. At reporting date, open monetary items use the closing rate. Exchange differences generally affect profit or loss, with exceptions in the standard. Apply the accounting policy that fits the transaction and seek qualified advice for decisions specific to the business.
Keep the event trail: quote, purchase commitment, receipt, vendor bill, payment, sale, collection, and report. A purchase order can show a commitment before a payable exists. Freight may still be an estimate when inventory arrives. Keep each event’s date, currency, and rate basis instead of replacing an old assumption with today’s rate.
These figures are for illustration only. They are not current rates or market benchmarks. A Philippine distributor receives a USD 50,000 goods quote. Using a planning rate of ₱56.00 per USD, procurement estimates a cost of ₱2,800,000 and saves that assumption with the purchase decision. Assume the USD 50,000 vendor bill is first recorded at ₱56.50 per USD. The payable is then ₱2,825,000 in the entity’s PHP books.
At month-end, the bill is still unpaid and the closing rate is ₱57.00. The payable is now ₱2,850,000, an illustrative ₱25,000 unrealized FX loss. If the company pays at ₱57.50, the PHP value at settlement is ₱2,875,000 before bank fees. That is ₱25,000 above the month-end value and ₱50,000 above the amount first recorded. Actual entries depend on accounting policy and timing. Check any prior revaluation so the loss is not counted twice.
Freight, duty, and brokerage bills that arrive later may change inventory cost or margin analysis under the company’s costing policy. They do not change the supplier’s USD price. If the goods are sold to a Singapore customer and invoiced in SGD, record that sale in SGD and convert it to PHP using the applicable rate. Review any open SGD receivable on its own; do not use USD/PHP movement as a stand-in for its value or the product’s margin.
The main problem is often keeping information in sync, not doing the math. Purchasing tracks supplier quotes, logistics tracks freight, payables tracks bills, and sales keeps price lists. Finance may update rates in another workbook. Each file can be internally consistent yet use a different date, supplier name, item code, cost estimate, or market definition.
That leads to repeated checks. Is the PO still open? Did sales get the new freight estimate? Is this rate for planning or accounting? Does the payable include an approved surcharge? Can the market report be traced to source transactions? ICAEW’s 2024 principles for good spreadsheet practice recommend controls that match spreadsheet risk and consistent working methods. Spreadsheets can still help with analysis. Risk grows when they are also the only source for approvals, rates, transaction details, and reports.
Control area | Spreadsheet-led management | Connected multi-currency workflow |
|---|---|---|
Supplier records | Terms, quote currencies, and item prices are copied between files. | Approved currencies, supplier terms, and purchase history stay linked to transactions. |
Exchange-rate consistency | Rates are pasted or replaced without a shared purpose or effective date. | Rate source, purpose, date, and approved overrides stay visible. |
Payable visibility | Open POs and unpaid bills have to be merged by hand. | Commitments, bills, balances, currencies, and due dates can be viewed separately. |
Pricing decisions | Price lists may use an old supplier quote or planning rate. | Pricing reviews can refer to stated assumptions and recorded costs. |
Variance analysis | FX, supplier price, freight, and discount effects are rebuilt after close. | Changes can be traced to source documents and grouped by cause. |
Reporting | Markets may use different definitions and conversion dates. | A defined reporting basis can link back to transactions and exceptions. |
A connected workflow does not force every team to use one rate. A pricing reference rate can differ from the bill’s accounting rate. The key is to show each rate’s purpose and effective date, and retain what was assumed, booked, and changed.
Start with a rate policy. Name the source, effective date, transaction-date rule, closing-rate process, and who can approve an override. Label planning, transaction, closing, and settlement rates. If a rate is corrected, keep the reason and history rather than silently changing an old purchase decision.
Link supplier details to purchase commitments. Save the quote currency, payment terms, deposits, approved item prices, expected payment date, and the assumptions used to approve the order. If a vendor bill differs from the PO, identify whether the reason is quantity, price, surcharge, or timing. Partial bills should not make the remaining commitment disappear from the cash outlook.
Oracle’s NetSuite guidance explains how vendor profiles can use a primary currency and additional transaction currencies. Its guide to currency on vendor transactions describes how the chosen currency can carry through purchasing documents. Such features help link steps in the process. Finance still needs clear rules, reliable supplier and item details, and suitable approvals.
Show the original foreign-currency amount alongside its base-currency carrying value and due date. Separate approved but unbilled purchase commitments from recorded bills. At settlement, match the amount paid, bank conversion, fees, and realized FX effect to the bill. Flag overdue balances, rate overrides, and invoices that no longer match approved supplier terms.
Once the supplier-to-payment workflow is clear, ask whether separate legal entities also need group accounting. The NetSuite OneWorld: Multi-Entity & Multi-Currency ERP Guide covers that question. Foreign-currency supplier payments alone do not mean a company needs multiple entities or a particular ERP edition.
Supplier price, payment FX, and landed cost answer different questions. Procurement compares supplier quotes and terms using approved planning assumptions. Finance tracks bills and payments under its accounting policy. Sales needs a current cost view when setting local prices. If freight is still an estimate, label the margin as estimated and update it when actual costs arrive. For more on freight and cost allocation, see Landed Cost Visibility for Trading Companies.
In a USD purchase, PHP books, and SGD sale, keep the SGD revenue and its PHP accounting value visible, alongside costs on a stated basis. If margin changes, check supplier price, FX, late freight, customer discounts, and sales-currency movement separately. Keep realized and unrealized FX on open monetary balances separate from product margin. Constant-currency comparisons can help explain a trend, but state the assumed rates and do not use them in place of booked results.
Keep reporting tied to the currency workflow: supplier terms, payables, pricing, and market results. For broader distribution context, see Softype’s ERP for Distributors page. For related finance topics, see International Accounting Issues: What Mid-Market CFOs Face in 2026.
Use these questions to decide whether the issue is foreign-currency transactions, multi-entity accounting, or both:
Transaction currency: Does each quote, PO, bill, payment, sale, and receipt keep its original currency and amount?
Entity base currency: Is the accounting currency defined for each entity, apart from supplier and customer currencies?
Rate source and timing: Can you identify the source, purpose, date, and approver for planning, transaction, closing, and settlement rates?
Open payables: Can payables show unpaid foreign-currency bills separately from approved but unbilled commitments?
Payment timing: Can finance see due dates, deposits, expected cash needs, and currency mismatches?
FX variance review: Can the team separate revaluation of open balances from settlement differences and supplier-price changes?
Supplier terms: Are currency, price, payment terms, and exceptions traceable from PO to bill?
Market reporting: Can leaders compare market revenue and margin using stated conversion and cost assumptions, while keeping original currencies available?
If one company buys and sells across currencies, start with controls for purchasing, payables, payments, pricing, and reporting. If separate legal entities keep their own books and need group or intercompany reporting, assess those needs too. Some businesses need both. Base the decision on the legal and reporting structure, not simply on the use of foreign currencies.
It is the careful handling of transactions in currencies other than the entity’s accounting currency. It includes keeping original amounts, recording rate basis and dates, reviewing open balances, tracking settlement effects, and reporting results on a clear basis.
They keep the quote, PO, and vendor bill in the agreed currency. They record the accounting value using the transaction-date rate required by policy, then track the foreign-currency payable through revaluation and payment.
Transaction currency is the currency on a particular invoice or payment. Group reporting currency is the currency used to present results across entities. An entity’s accounting or functional currency is separate and should not be inferred from the supplier’s currency.
Unrealized FX is the change in value of an open foreign-currency balance at a reporting date. Realized FX occurs when the balance is paid or collected at a different currency value. Check prior revaluation so an earlier change is not counted twice.
No. One legal entity can buy from a USD supplier and sell in SGD while keeping its books in PHP. Separate entities may add accounting and group-reporting needs, but foreign-currency transactions alone do not require them.
Set a rate hierarchy with named sources and dates. Define which rate applies to approval, accounting, period-end revaluation, settlement, and pricing. Limit overrides and keep a history of the rate used for each event.
Look for repeated manual merges between quotes, POs, bills, payments, and price lists; rate changes that cannot be traced; unknown exposure by currency and due date; or market margin that cannot be tied to source transactions. These control gaps matter more than any fixed number of currencies.
Map a supplier purchase from quote to payment and identify the rate decisions, files, and reporting handoffs that need attention.
Helping businesses thrive with integrated ERP solutions.
NetSuite
Service
Company
Contact Us
Copyright © 2026


