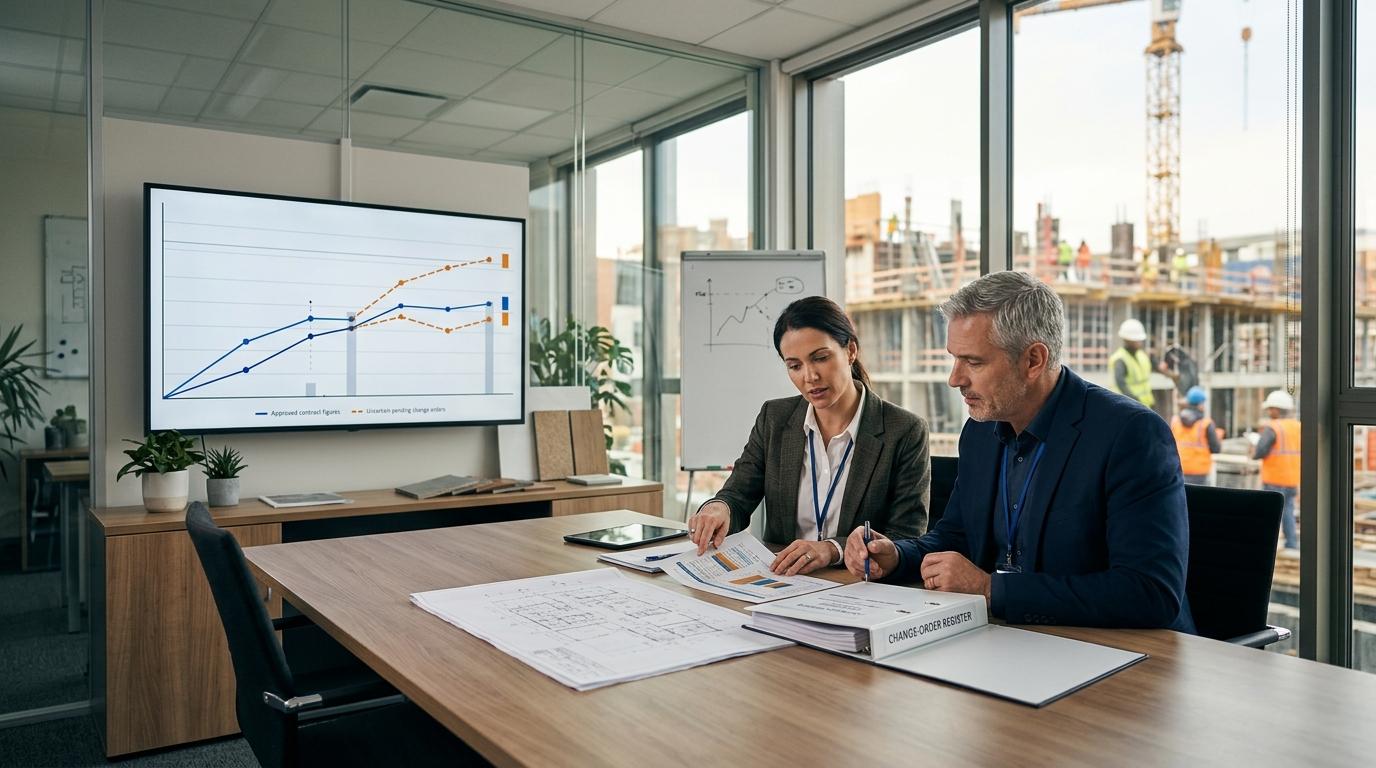
Pending change orders and project margin are linked as soon as crews begin work on a scope change the customer has not approved or priced. The approved contract value may be correct, yet the forecast can still miss the cost of labor, materials, subcontract commitments, and schedule effects tied to that work.
Answer: Approved-only reporting can overstate the margin picture when the forecast includes approved revenue but omits costs already incurred or expected on pending scope. Keep approved contract value separate from potential recovery, and show incurred cost, open commitments, and remaining cost exposure in the base forecast. Model possible recovery in a separate, evidence-based scenario—not as approved revenue or an accounting conclusion.
Approved-only reporting can describe the authorized scope accurately and still fail to describe the work underway. If the job report subtracts only the cost of approved scope from approved contract value, it may miss costs accumulating against a potential change order or an unapproved scope of work.
Some costs have happened but may not appear in the report yet. Timesheets may still be under review. Supplier bills may be late, and received materials may not be coded. A subcontractor may have done the work but not sent a payment claim. Other costs are committed or still ahead, such as open purchase orders, remaining subcontract work, labor, supervision, and rentals.
Keep these costs separate. Incurred cost covers work already done. Commitments cover future costs the company has agreed to pay. Remaining cost covers work not yet done or committed. As a commitment becomes a receipt, invoice, or posted cost, update its balance so you count it only once. An open purchase order is not an incurred expense, but its unpaid balance belongs in the cost-to-complete estimate.
A change can also extend the schedule and raise costs for supervision, equipment rental, site support, or overtime. Do not assume the customer will cover these costs. Include supported estimates in the internal forecast when the change affects delivery.
Scope changes become margin exposure as soon as field work begins.
A change-aware view keeps the approved commercial baseline intact while making execution exposure and potential recovery visible.
Measure | Approved-only reporting | Change-aware forecast |
|---|---|---|
Approved revenue | Authorized contract value and approved changes | Same approved value; pending requests stay separate |
Pending scope | May be absent or isolated in a change log | Tracked by status, owner, and execution progress |
Costs incurred | Often limited to posted costs coded to approved scope | Includes performed pending-scope work and supported unposted costs |
Remaining cost exposure | Unused approved budget may stand in for cost to finish | Open commitment balances plus current remaining-work estimate |
Forecast margin | One figure that can omit pending costs | Base case plus separately labeled recovery scenario |
Decision usefulness | Shows approved scope in isolation | Shows margin dependency, downside, and items needing action |
Capture cost exposure when the change is identified, not only when commercial approval arrives. The American Institute of Architects’ current document listing identifies G714–2017, Construction Change Directive as the applicable edition. It provides for directing work to proceed before the owner and contractor agree on contract sum or time; the contract and local requirements determine what applies to a specific project.
For private construction contracts in the Philippines, the Construction Industry Authority of the Philippines’ Revised CIAP Document 102 (2022 Edition) was approved in 2022 and took effect on February 1, 2023, according to CIAP. It addresses written change orders for variations. It applies to private construction; government contracts use CIAP Document 101.
Identify scope. Log the instruction, date, source, affected drawings, and potential entitlement. Note any work already performed, early cost range, and immediate commitments. Do not increase approved contract value.
Give notice. Record the notice deadline, submission, and proof of delivery. A missed notice may affect recovery rights, but it does not erase the cost exposure from the internal forecast.
Price the change. Estimate labor, materials, equipment, subcontract work, and supported time effects. Keep estimated delivery cost separate from the proposed customer price.
Submit and track review. Record requested value, date, customer decision-maker, questions, negotiation status, and next response date. Refresh incurred costs, commitments, and remaining cost to complete while the client reviews.
Resolve approval or rejection. On approval, move only the agreed amount into approved contract value. For partial settlement or rejection, retain incurred costs and unavoidable obligations, reassess avoidable remaining work, and update any supported recovery scenario.
Update the budget and forecast. Reconcile the authorized budget, cost coding, billing position, and forecast. Remove approved recovery from the pending view so it is not counted twice; reconcile existing costs into the revised structure.
One “pending” status hides important differences. Track commercial status (identified, priced, submitted, negotiating, approved, rejected), execution status (not started, underway, complete), and financial status (incurred, committed, billed) separately.
The base case shows the project using approved revenue and current cost exposure. Calculate it as approved contract value minus current estimate at completion (EAC). Include approved-scope costs, costs already incurred on pending work, open commitment balances, the cost of remaining work, and supported schedule impacts. Do not include recovery from unresolved changes.
The expected view answers a different question: how might potential recovery affect the internal commercial outlook? Add probability-weighted potential recovery as a separate line. Where full, partial, and zero recovery are plausible, estimate each outcome and its likelihood rather than applying one automatic percentage to the submitted amount. If an outcome changes the work still required, adjust that scenario’s cost as well.
To see where pending scope may be affecting your controls, assess your construction project controls with Scout by Softype.
Each probability assumption needs a named commercial owner, supporting evidence, an assessment date, and a next review date. Evidence can include contract terms, authorized directions, notices, correspondence, accepted quantities, and negotiation history. A finance reviewer should challenge important assumptions. A probability helps with planning; it does not approve a change, prove a right to payment, authorize billing, or decide how revenue is recorded.
Contract terms, supporting records, and accounting policies affect revenue recognition. IFRS 15 was issued in 2014 and is effective for annual reporting periods beginning on or after January 1, 2018; the IFRS Foundation provides the current issued text. It sets rules for contract changes and variable consideration. Treat that accounting review separately from internal probability estimates, and ask qualified accounting and legal advisors to review the contract and facts.
Softype’s related guide, Managing Project Costs Before They Become Margin Problems, explains cost-to-complete and commitment controls that support this change-aware forecast.
Illustrative example only. Assume a fixed-price project has ₱20.0 million of approved contract value and ₱16.0 million forecast cost for approved scope. Crews have started a client-directed pending change. Its ₱1.5 million total cost will be incurred under the current execution plan regardless of the pricing outcome.
Pending-change cost exposure | Amount | Classification |
|---|---|---|
Additional labor performed | ₱300,000 | Incurred; partly unposted |
Materials consumed | ₱250,000 | Incurred |
Subcontract work performed | ₱200,000 | Incurred; supplier invoice pending |
Remaining materials and subcontract work | ₱350,000 | Unperformed open commitments only |
Remaining labor and equipment | ₱250,000 | Uncommitted cost to complete |
Incremental supervision and rentals | ₱150,000 | Supported schedule-related estimate |
Total pending-change cost | ₱1,500,000 | Count each cost once |
The contractor has submitted a ₱2.0 million proposal. For illustration, the owner’s commercial lead documents three internal outcomes: 50% probability of full acceptance (₱2.0 million), 30% probability of partial settlement (₱1.0 million), and 20% probability of no recovery. Expected potential recovery is ₱1.3 million. These are example assumptions, not recommended defaults.
Forecast view | Approved value | Potential recovery shown separately | Forecast cost | Profit | Margin |
|---|---|---|---|---|---|
Approved-scope report (incomplete cost view) | ₱20.0M | — | ₱16.0M | ₱4.0M | 20.0% |
Base case: full cost, no recovery | ₱20.0M | ₱0 | ₱17.5M | ₱2.5M | 12.5% |
Expected recovery scenario | ₱20.0M | ₱1.3M | ₱17.5M | ₱3.8M | 17.8% |
Full recovery scenario | ₱20.0M | ₱2.0M | ₱17.5M | ₱4.5M | 20.5% |
Scenario margins use the relevant scenario revenue as the denominator. The original 20% view was overstated because the forecast omitted ₱1.5 million of expected cost, not because approved revenue was wrong. The base case exposes a 12.5% margin without pending recovery; the 17.8% expected view depends on a separately modeled potential recovery. Neither scenario states what revenue is recognized for financial reporting.
A shared forecast connects pending changes to project cost and margin.
Scope identification: unique reference, source, date, affected work, and potential entitlement recorded.
Notice: deadline, responsible owner, evidence of timely notice, and follow-up captured.
Pricing: cost estimate separated from proposed customer price; schedule effects supported.
Submission: amount, date, supporting detail, and customer decision-maker recorded.
Customer status: review, negotiation, partial approval, dispute, rejection, or approval current.
Cost capture: incurred labor, materials, and subcontract costs visible, including credible unposted work.
Commitments: open balance reconciled against incurred cost and invoices to avoid duplication.
Probability owner: named commercial owner and finance reviewer assigned.
Evidence: instructions, notices, correspondence, quantities, and pricing support retained.
Next review date: set with triggers for earlier reassessment.
Approval or rejection: approved value moved into the authorized contract view; rejected recovery removed or explicitly retained only where separately supported.
Review material or fast-moving changes weekly with project management, commercial/contracts, cost control, procurement, and finance. Confirm what was instructed and performed, reconcile incurred costs against timesheets and field progress, update open commitments, and rebuild remaining cost from current quantities and schedule. Ask each probability owner to confirm the evidence, assessment date, and next review date.
At the monthly forecast and WIP review, compare the prior margin view with the current one. Note changes in approved revenue, costs, commitments, remaining work, schedule impacts, and potential recovery. When a change is resolved, update the budget, forecast, billing position, and accounting review. This helps leaders see whether margin fade comes from rising costs, changed recovery assumptions, or both.
Softype’s overview, NetSuite for Construction: Project Tracking & Job Costing ERP, covers the project-tracking context behind this kind of margin review.
It can pair correct approved revenue with a cost forecast that excludes pending-scope labor, materials, subcontract work, commitments, or schedule impacts. The revenue baseline may be accurate while the forecast fails to include the work actually being performed.
Capture the cost in the internal forecast as the work is performed, with supporting quantities and cost coding. Finance should separately determine the appropriate accounting entries and revenue treatment under the contract and applicable policies.
The base case uses approved contract value and current total cost exposure, without assuming pending recovery. The expected scenario displays potential recovery separately using documented outcomes and assumptions.
Use a unique change reference to connect labor, materials, subcontract activity, and purchase commitments. Separate incurred cost, unperformed commitment balances, and uncommitted remaining work; reconcile balances as invoices and receipts post.
A named commercial or contracts owner should support the recovery assessment with evidence. A finance reviewer should challenge material assumptions and ensure the probability, rationale, and review date remain visible.
No. Probability-weighted recovery is an internal forecasting view. It does not create approval, contractual entitlement, or an accounting conclusion; revenue recognition requires a separate assessment.
Review active material changes weekly, then reconcile costs, commitments, assumptions, and WIP during the formal monthly forecast. Increase review frequency when execution or commercial exposure changes quickly.
Helping businesses thrive with integrated ERP solutions.
NetSuite
Service
Company
Contact Us
Copyright © 2026


